Key takeaways
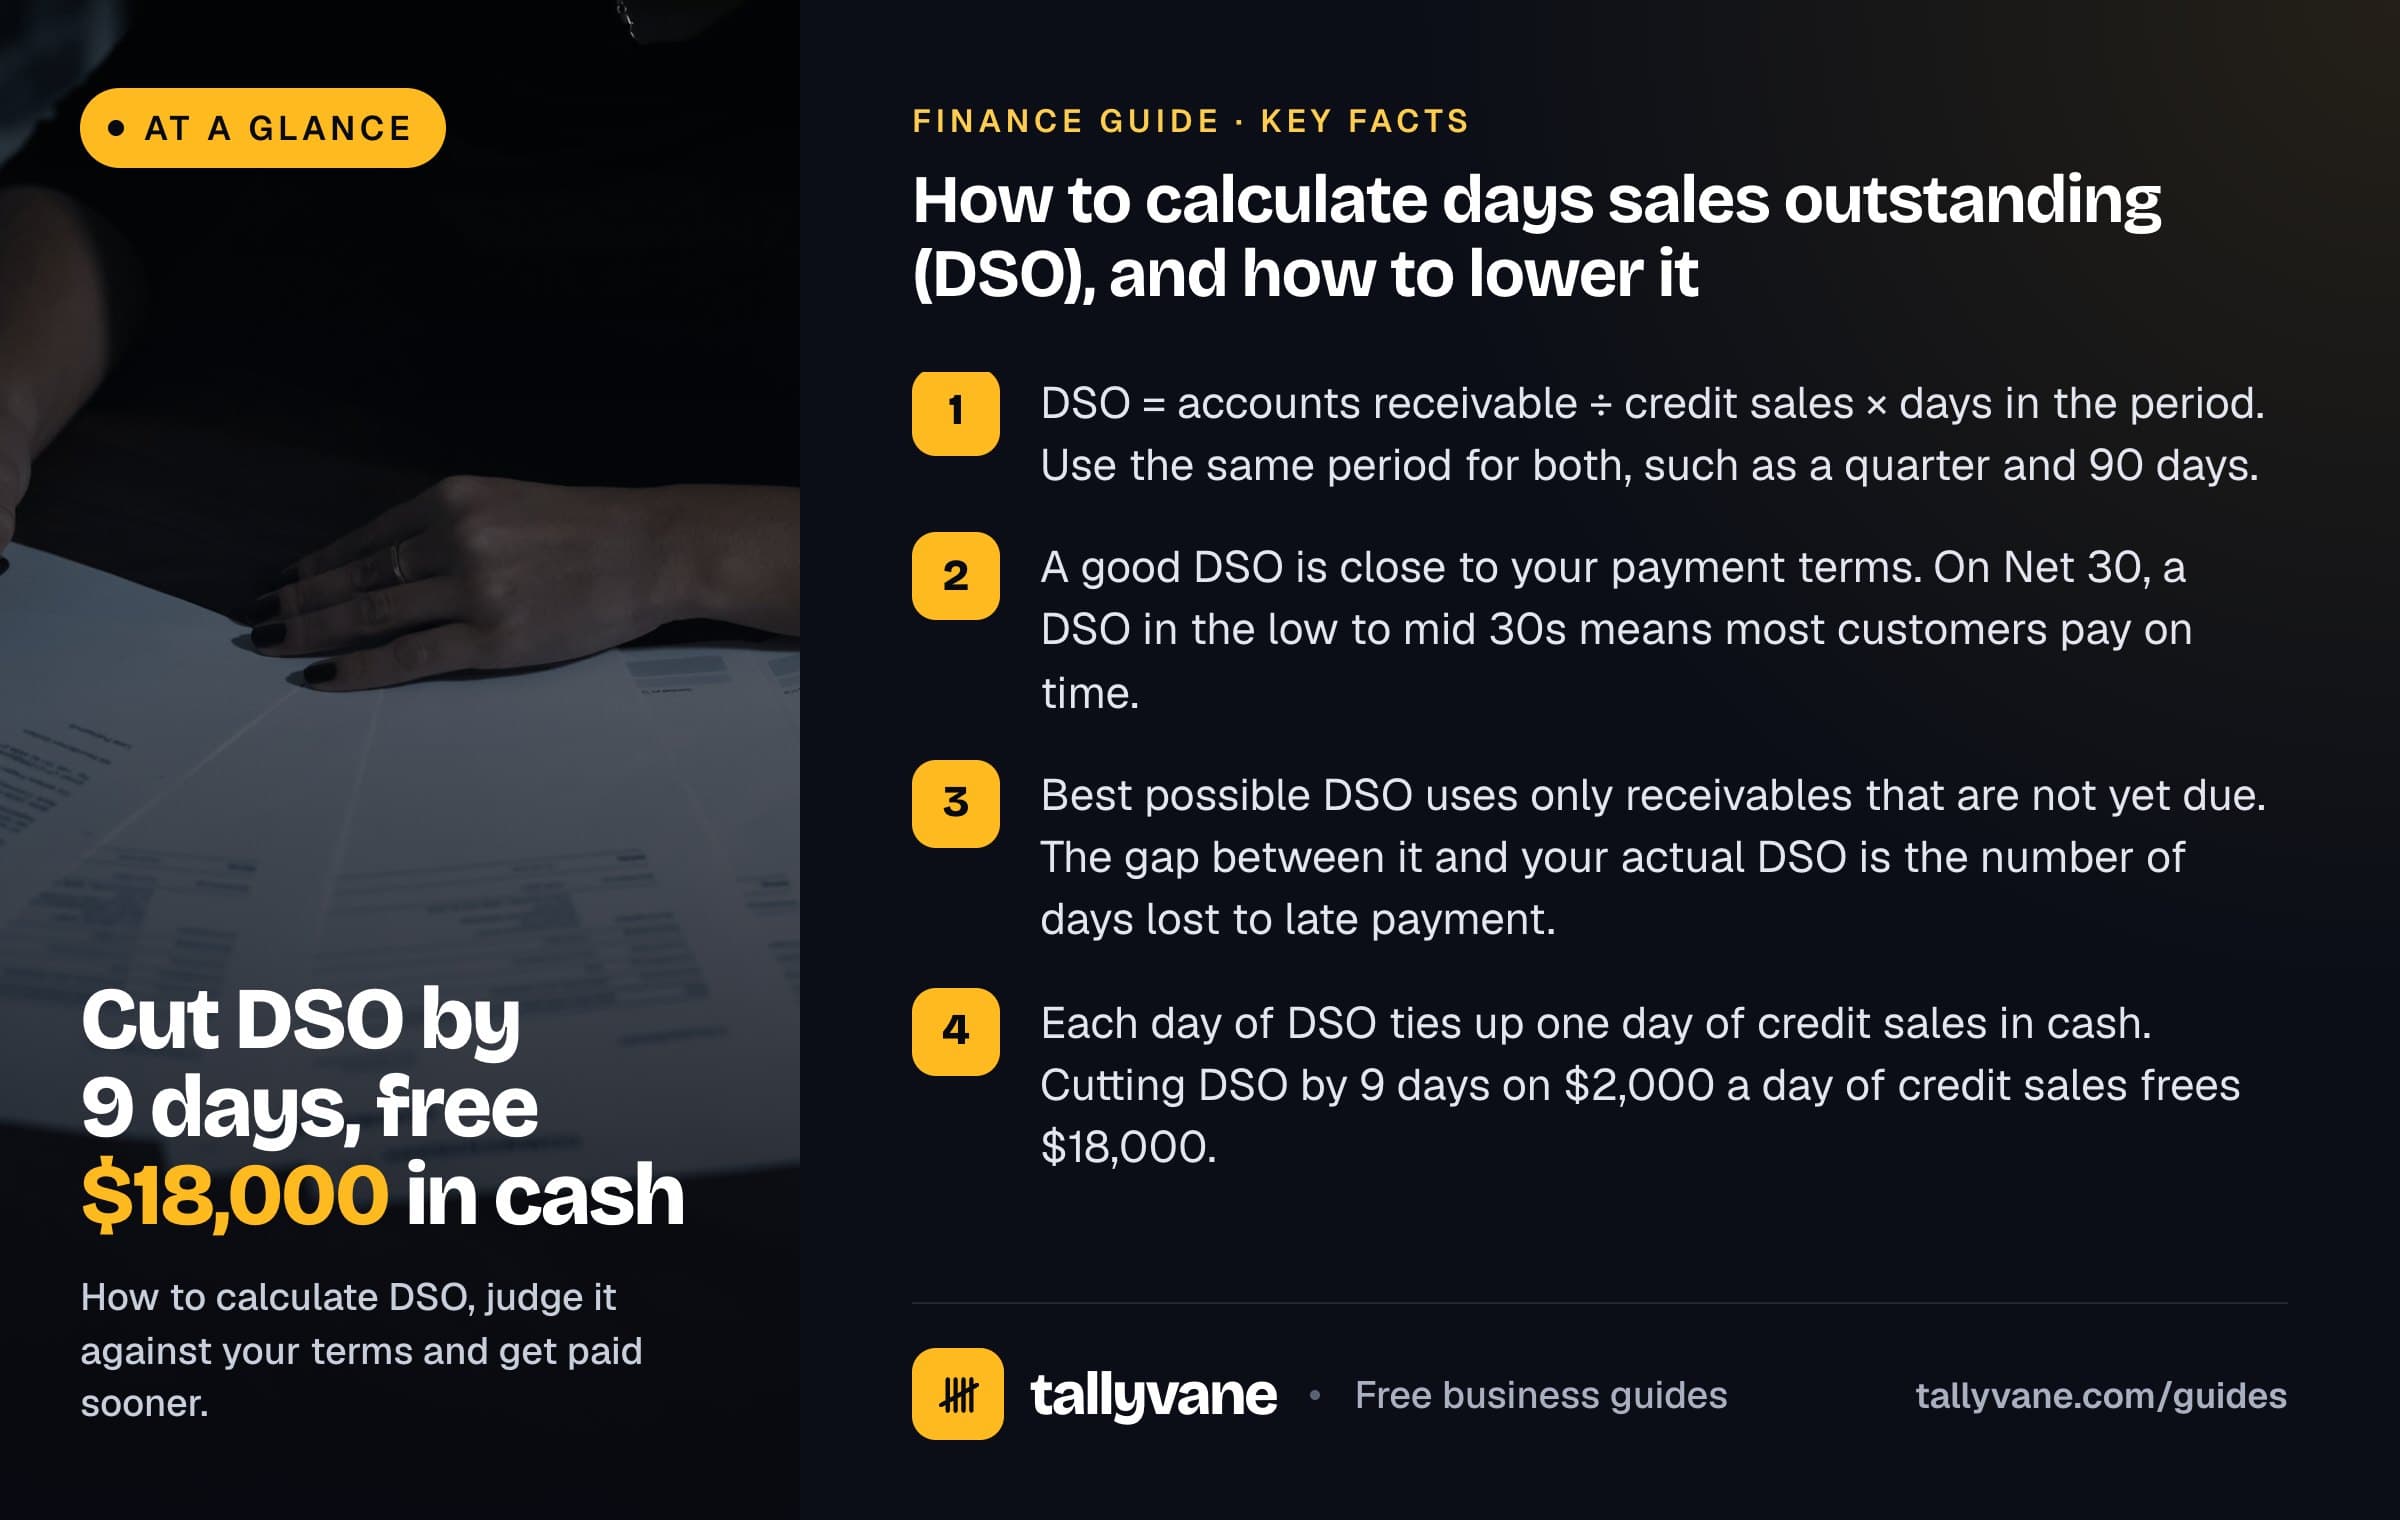
- DSO = accounts receivable ÷ credit sales × days in the period. Use the same period for both, such as a quarter and 90 days.
- A good DSO is close to your payment terms. On Net 30, a DSO in the low to mid 30s means most customers pay on time.
- Best possible DSO uses only receivables that are not yet due. The gap between it and your actual DSO is the number of days lost to late payment.
- Each day of DSO ties up one day of credit sales in cash. Cutting DSO by 9 days on $2,000 a day of credit sales frees $18,000.
What DSO measures
When you sell on credit, the sale shows up in revenue straight away but the cash arrives later. The unpaid invoices sit on your balance sheet as accounts receivable. DSO turns that balance into a number of days: on average, how long it takes to collect a sale.
It is also called the average collection period. A rising DSO is often the first sign of a cash squeeze, because profit can look healthy on the profit and loss statement while more and more of it is stuck in customers’ hands.
DSO only matters if you invoice customers and let them pay later. A shop or online store paid at checkout has almost no receivables, and its DSO will be close to zero.
The DSO formula
Divide accounts receivable by credit sales for a period, then multiply by the number of days in that period. Use 30 or the actual days for a month, 90 or 91 for a quarter, and 365 for a year. The days must match the sales figure.
Use credit sales, not total sales, if you have both. Cash and card sales paid on the spot never become receivables, so including them makes DSO look shorter than customers’ real payment habits. If almost every sale is invoiced, total revenue is close enough.
For the receivables figure you have two choices. Ending receivables is simple and shows where you stand today. Average receivables, the opening balance plus the closing balance divided by two, smooths out a single big invoice at month end. Pick one and use it every period so the trend means something.
The financial ratios calculator works out DSO and receivables turnover for you. Enter receivables at the end of the period, credit sales and the days in the period. Add receivables at the start of the period and it uses the average instead of the end balance.
DSO = Accounts receivable ÷ Credit sales × Days in period Average receivables = (Opening receivables + Closing receivables) ÷ 2
Worked example: a commercial cleaning company
A commercial cleaning company invoices its office clients monthly on Net 30 terms. In the third quarter, 90 days, it made $180,000 of credit sales. Receivables were $66,000 at the start of the quarter and $78,000 at the end. Of the $78,000, $54,000 is not yet due and $24,000 is overdue.
To reproduce it in the financial ratios calculator, enter $78,000 as accounts receivable, $66,000 as receivables at the start, $180,000 of credit sales and 90 days. Leave the start figure blank to see DSO on ending receivables.
- On Net 30 terms, a DSO of 36 to 39 days means customers are paying about a week late on average.
- Ending DSO is higher than average DSO because receivables grew during the quarter. Watch whether that continues.
- Every day of DSO holds back $2,000. Getting from 39 days down to 30 would free $18,000 of cash without making a single extra sale.
| Figure | Working | Result |
|---|---|---|
| Average receivables | ($66,000 + $78,000) ÷ 2 | $72,000 |
| DSO on average receivables | $72,000 ÷ $180,000 × 90 | 36 days |
| DSO on ending receivables | $78,000 ÷ $180,000 × 90 | 39 days |
| Receivables turnover for the quarter | $180,000 ÷ $72,000 | 2.5 times |
| Best possible DSO | $54,000 ÷ $180,000 × 90 | 27 days |
| Days lost to late payment | 39 − 27 | 12 days |
| Credit sales per day | $180,000 ÷ 90 | $2,000 |
DSO and receivables turnover
Receivables turnover is the same information the other way round. It tells you how many times in a period you collect your average receivables balance. Divide the days in the period by the turnover and you get DSO.
In the example, turnover of 2.5 times in a 90-day quarter gives 90 ÷ 2.5 = 36 days, the same as the average-receivables DSO. Over a full year at the same pace, turnover would be 10 times and DSO 36.5 days. A higher turnover is better; a lower DSO is better.
The financial ratios guide uses year-end receivables and a full year of revenue, which suits an annual check. For managing collections, work it out monthly or quarterly so a slowdown shows up while you can still act on it.
Receivables turnover = Credit sales ÷ Average receivables DSO = Days in period ÷ Receivables turnover
What is a good DSO?
There is no single good number, because DSO depends on the terms you offer. A business that bills on Net 60 cannot expect a 30-day DSO. The useful comparison is your DSO against your own standard terms.
A common rule of thumb is that DSO within about a third above your terms is acceptable: up to about 40 days on Net 30. Treat that as a starting point, not a target. Industry averages vary widely, and many large customers pay on their own schedules.
| DSO | What it usually means |
|---|---|
| Under 30 days | Customers pay early or on time, or you take deposits up front. |
| 30 to 40 days | Most customers pay roughly on time. Normal for Net 30. |
| 40 to 60 days | A sizeable share of invoices are paid late. Review reminders and who you give credit to. |
| Over 60 days | Collections are a real problem, or a few large debts may never be paid. Check your aged receivables. |
Best possible DSO: separating terms from late payment
DSO mixes two things: the credit you chose to give, and the extra time customers take. Best possible DSO isolates the first. It uses only current receivables, the invoices that are not yet due, so it shows what DSO would be if every customer paid exactly on the due date.
The gap between your actual DSO and best possible DSO is the cost of late payment, in days. In the example, 27 days comes from the terms and 12 days from customers paying late. If the gap is small but DSO is still high, the fix is shorter terms. If the gap is large, the fix is collections.
Your accounting software’s aged receivables report gives you the split between current and overdue invoices. Compare it with last quarter’s to see whether the overdue share is growing.
Best possible DSO = Current (not yet due) receivables ÷ Credit sales × Days in period
How to lower DSO
Most of the gain comes from a few habits applied to every invoice. Start with whichever matches your biggest gap.
- Shorten your terms for new customers: Net 14 or Net 15 instead of Net 30. Agree them in writing before the work starts.
- Take a deposit or bill in stages on large jobs, for example 30% up front, 40% at a midpoint and 30% on completion.
- Invoice the same day you finish or deliver. Every day an invoice sits unsent is a day added to DSO.
- Make paying easy: bank transfer details, a card payment link and a clear due date on every invoice.
- Send reminders on a schedule: a few days before the due date, the day after, and then weekly.
- Charge a late fee where your contract and local law allow it, and say so on the invoice up front.
- Run a credit check, or ask for payment up front, before giving terms to a new customer with a large order.
- Think twice about early-payment discounts. Offering 2/10 Net 30 costs you about 37% a year on the money that comes in 20 days early.
Mistakes that distort DSO
DSO is easy to calculate and easy to misread. Watch for these before you act on the number.
- Mixing periods: monthly sales with 365 days, or annual sales with 30 days. The days must match the sales.
- Seasonal swings: a business that bills heavily in December will show a high year-end DSO even if customers pay on time. Compare the same month year on year.
- Including sales tax in receivables but not in sales. Invoices usually include tax, so use sales including tax or strip the tax from receivables.
- Ignoring bad debts. Old invoices you will never collect inflate DSO. Write them off so the figure reflects collectable debts.
- Looking at the average only. One large customer paying 90 days late can hide behind a reasonable DSO. Check the aged receivables report customer by customer.